
Rate: Home, Finance & Wellness
- Rating
- 4.5
- Downloads
- 500.00K
- Content Rating
- Everyone
Rate: Home, Finance & Wellness - Screenshots
Pros
- Combines budgeting
- wellness
- and home tracking in one app
- Simple rating system makes daily check-ins quick
- Useful for spotting patterns in spending and personal habits
- Clean interface is approachable for first-time users
- Can encourage more consistent reflection and routine building
Cons
- May feel too broad for users seeking a dedicated finance app
- Manual entries can become repetitive over time
- Wellness ratings are subjective and may lack deeper guidance
- Limited value if you prefer detailed reports or advanced analytics
- Some features may require account access or paid upgrades
Rate: Home, Finance & Wellness - Description
- App Name
- Rate: Home, Finance & Wellness
- Package Name
- com.guaranteedrate.superapp
- Developer
- Guaranteed Rate, Inc
- Category
- Finance
- Last Updated
- May 11, 2023
- Version
- 1.52-prod
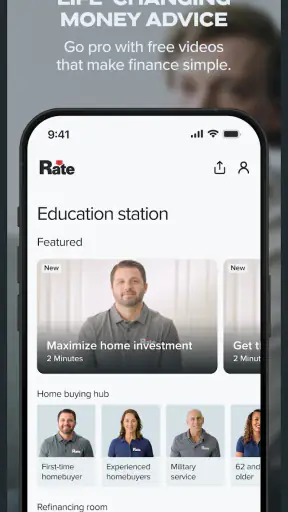
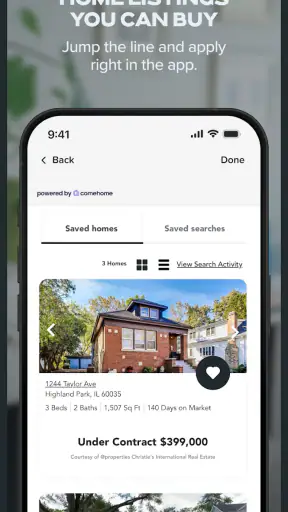
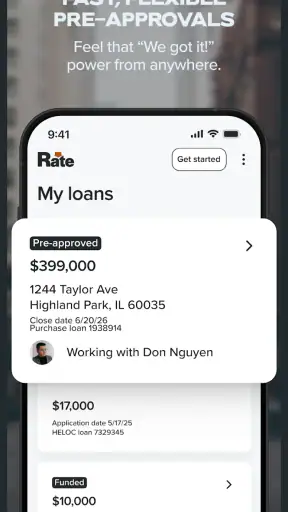
I found Rate: Home, Finance & Wellness most useful when I treated it as a starting point for several money decisions rather than as a complete financial command center. It brings mortgage, refinancing, auto, home-equity, and personal-loan topics into one app, while also adding travel and wellness content. That combination makes it unusual: it is not simply a calculator, a banking app, or a loan marketplace in the narrow sense. It is a finance-focused app from Guaranteed Rate, Inc that tries to keep borrowing, home ownership, and parts of everyday planning in the same place.
My overall view is positive, with an important qualification. I would recommend it to someone actively thinking about a home loan, refinancing, or another major borrowing decision and wanting a convenient place to begin. I would be less enthusiastic about using it as my only source for comparing financial products, tracking a full household budget, or managing accounts I already hold elsewhere. Its value is strongest during a decision-making period, not necessarily as an app I would open every day forever.
What the app is really good at
The clearest strength is its broad scope. Mortgage research can easily become scattered across lender pages, calculators, notes, email threads, and conversations with professionals. Rate gives that process a more focused home on a phone. I can move from thinking about a purchase to considering refinancing, home equity, an auto loan, or a personal loan without switching to an unrelated finance service each time.
That matters because borrowing choices are connected. A homeowner considering a renovation may wonder whether home equity makes sense, whether a personal loan would be simpler, or whether refinancing changes the wider monthly picture. The app does not eliminate the need to examine terms carefully, but having these subjects together encourages a more sensible comparison than jumping between disconnected searches.
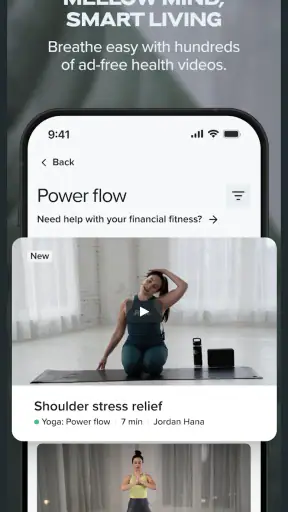
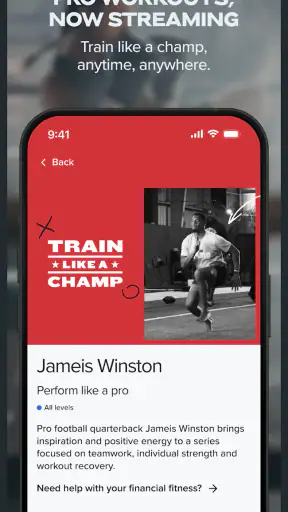
I also like that the app is not limited to property finance. The travel and wellness elements broaden its purpose, although they do not automatically make it a replacement for a dedicated travel planner, health app, or money-management tool. For me, those additions work best as supporting content around a larger financial journey rather than as the main reason to install it.
The app is free, which lowers the barrier to trying it during the early research stage. It is aimed at everyone from an age-rating perspective, and it supports devices running Android 7.0 or later. That makes it accessible to people who may not have a recent phone, though the experience can still depend on the device and operating system available to each user.
Its public reception is encouraging: it holds a 4.5 average from around 2K ratings, with over 500K installs and 239 written reviews. I would not treat those figures as proof that it will fit every borrower, but they do suggest that the app has reached a meaningful audience and that many users find enough value to rate it favorably.
A practical home-buying scenario
Imagine I am renting now but considering a first home. My first mistake could be focusing on the maximum amount a lender might approve instead of the payment I would actually be comfortable carrying. In that situation, I would use Rate to organize my initial thinking around mortgage options, then write down the questions that remain: how much cash would I need upfront, how would taxes and insurance affect the monthly cost, and what would happen if my income or expenses changed?
The useful insight is not simply finding a loan topic in an app. It is creating a pause between curiosity and commitment. I can use the app to identify the kind of financing I need, but I should then compare the complete cost, repayment structure, and conditions through official documents and direct conversations. That two-step workflow is more responsible than treating an attractive estimate as a promise.
For a homeowner considering refinancing, the same approach is even more important. A lower rate can sound appealing while fees, a changed loan term, or a longer repayment period alter the real outcome. I would use the app to frame the question, then calculate the break-even point: how long I would need to keep the new loan before the costs were recovered. If I expected to move soon, refinancing might be a poor choice even if the headline rate looked better.
That is one of the app’s less obvious benefits. It can help me move from a vague thought, such as “perhaps I should refinance,” toward a more precise decision: “What costs would I pay, how much would the payment change, and how long would I stay?” The final answer still requires careful review, but the app can make the starting question more concrete.
Why its wider loan coverage is useful
Many financial apps concentrate on one task. A budgeting app may be excellent for categorizing spending but offer little help with a mortgage. A bank app may show my existing accounts but only present that institution’s borrowing products. A generic calculator may produce a number without helping me understand which type of financing I am considering. Rate sits somewhere different by connecting several major borrowing subjects in one experience.
That can be particularly helpful when a financial need changes shape. A car purchase might begin as an auto-loan question, but an unexpected repair could lead someone to consider a personal loan instead. A home project could raise the question of home equity. Having these categories nearby makes it easier to notice that the most familiar option is not always the most suitable one.
Still, convenience should not be confused with neutrality. When an app is associated with a particular developer, I naturally pay closer attention to whether I am learning broadly or being guided toward one provider’s process. Guaranteed Rate, Inc is clearly identified as the developer, so I would use the app as an informed first stop while keeping my comparison process wider than the app itself.
My practical method would be to record the same details for every option: total borrowing cost, payment schedule, fees, flexibility, and consequences of paying early or late. I would not compare a monthly payment from one product with an advertised rate from another and call that an apples-to-apples comparison. The app can help me locate the subject; my notes and the formal terms should determine the decision.
The travel and wellness additions
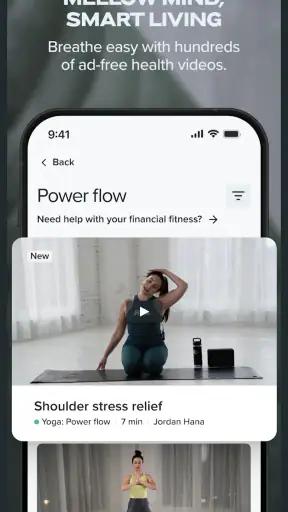
The travel and wellness sections make the app feel broader than a conventional mortgage tool. I can understand why they are included: housing, money, lifestyle, and personal well-being often overlap in real life. A move may affect travel plans, and financial stress can affect wellness. In that sense, the extra areas give the app a more rounded identity.
My reservation is that breadth can also dilute focus. If I am opening the app to investigate a home-equity decision, I do not necessarily want unrelated material competing for attention. Likewise, someone searching primarily for travel planning or wellness guidance may find a finance-centered app too specialized in the wrong direction. The additions are welcome, but I would judge the app mainly by how well it supports financial decisions.
A useful way to handle this is to treat the lifestyle material as context rather than authority. I might use it to think about how a financial choice fits into a larger plan, but I would not expect it to replace a dedicated travel service or a purpose-built wellness application. That distinction keeps expectations realistic and prevents the app from being judged for jobs it was not designed to perform.
Where the experience needs caution
The main weakness is the risk of mistaking convenience for completeness. A finance app that gathers many topics can make a complex decision feel tidy before the difficult details have been examined. Mortgages, refinancing, home equity, auto loans, and personal loans all have different risks and conditions. A clean mobile experience cannot remove that complexity.
I would be especially careful with any figure that appears to make affordability look simple. A monthly payment is only one part of the picture. I would also consider total repayment, fees, changing circumstances, insurance, taxes, maintenance, and the possibility that my income could fall. For a home loan, I would avoid making a decision based on the payment alone. For a personal loan, I would ask whether borrowing solves the underlying problem or merely delays it.
There is also a comparison limitation. The usual alternative for a borrower is to visit several lenders, speak with a broker, use independent calculators, and read official disclosures. Rate may make the first stage less frustrating, but it should not become the only comparison point. If I wanted a broad market view, I would deliberately consult sources outside the app rather than assuming that one convenient destination represents every available path.
Another limitation is that the app may be more valuable to an active borrower than to someone seeking long-term financial organization. I would not install it expecting the same role as a spending tracker, investment dashboard, bill organizer, or complete banking replacement. Its emphasis is on financial subjects connected to borrowing, housing, travel, and wellness. That is a defined purpose, and it is better to respect that purpose than to demand features belonging to another category.
The current version is 1.52-prod, and the app was released on May 11, 2023. Those details place it in a relatively modern mobile-app context, but they do not tell me how every screen will behave on every phone. I would keep the application updated through the normal app-store process and pay attention to whether it remains comfortable on my particular device. A finance app should feel clear and stable before I trust it as part of a major decision workflow.
Questions I would answer before relying on it
The first question is whether the app is suitable for someone who is only browsing. Yes, that is where I think it makes the most sense. Early research is a good time to explore categories, clarify vocabulary, and prepare questions. I would not interpret browsing as an obligation to apply for anything. The app is most useful when it helps me become a more informed participant in the next conversation.
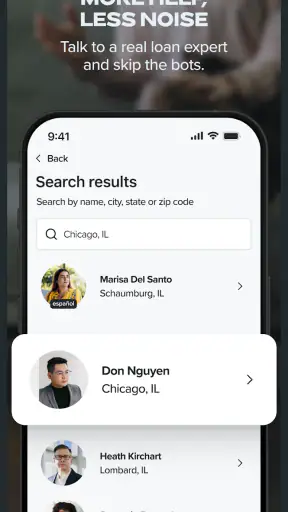
The second question is whether it can replace a professional adviser. I would say no. A lender, broker, accountant, or financial adviser can consider personal circumstances that a general mobile experience cannot fully understand. I would use Rate to prepare for those conversations, not to avoid them when the decision is large, complicated, or difficult to reverse.
The third question is whether it is useful for existing homeowners rather than first-time buyers. Yes. Refinancing and home-equity topics give it a reason to remain relevant after a purchase. However, the same caution applies: I would compare the long-term effect, not just the immediate payment, and I would consider how long I expect to keep the property or loan.
The fourth question is whether the free price creates a catch. The app itself is free to download, which makes experimentation easy. But free access should not be confused with free borrowing. Loans have their own costs and conditions, so I would inspect the actual terms of any financial product separately from the cost of using the app.
The fifth question is who should skip it. I would skip it if my main goal were detailed expense tracking, investment management, account aggregation, or specialist travel and wellness planning. I would also look elsewhere if I wanted an entirely independent comparison environment and did not want to begin with an app developed by a lender. In those cases, a dedicated budgeting tool, independent comparison service, or direct research across multiple providers would be a better fit.
Small workflow choices that improve the result
My first tip is to open the app with a written question, not just a general hope of finding a good deal. “Can I afford a home?” is too broad. “What information do I need before comparing a mortgage?” is more useful. A focused question helps me notice gaps and prevents me from wandering through categories without learning anything actionable.
My second tip is to separate education from commitment. I would explore mortgage, refinancing, auto, home-equity, and personal-loan material during the research phase, but I would not submit information or make a decision until I had checked the full terms elsewhere. This creates a useful boundary between understanding a product and agreeing to it.
My third tip is to use the app alongside a simple personal worksheet. I would record the purpose of the loan, the amount I think I need, the payment I could manage comfortably, the total cost, and the event that would make the loan unaffordable. This is more revealing than focusing on the best-looking number. It also helps me compare a home-equity option with a personal loan without changing my standards halfway through.
My fourth tip is to revisit the decision after a short pause. Borrowing decisions can feel urgent, especially when connected to a home purchase or a necessary repair. After researching in the app, I would wait long enough to reread my notes and ask whether the loan solves a durable need. If the answer changes when the excitement fades, that is valuable information.
My fifth tip is to keep the travel and wellness material in its proper place. I might use those sections to think about how a loan affects lifestyle priorities, but I would not let attractive lifestyle ideas encourage unnecessary borrowing. A travel goal or home improvement plan should fit the budget first; the app should support that judgment rather than replace it.
Who will get the most from it
I think the strongest audience is a person at a financial crossroads: a prospective homebuyer, a homeowner examining refinancing, someone considering home equity, or a borrower comparing an auto loan with a personal loan. These users benefit from having related subjects gathered in one place and from being able to approach the next step with better questions.
It can also suit someone who prefers researching on a phone rather than starting with a desktop browser and a pile of lender pages. The mobile format makes the app convenient for short sessions: I can investigate a topic, note what I need to verify, and return later. That is a modest advantage, but it matters when financial research is spread across commutes, lunch breaks, or evenings at home.
I would be more cautious recommending it to a financially experienced user who already has a well-developed comparison system. That person may find the broad categories convenient but not especially necessary. Someone who wants a neutral, all-provider view may also prefer an independent service from the beginning. The app’s best role is as a structured entry point, not as a universal answer for every financial personality.
For families, the app can be useful as a conversation aid. Two people considering a home purchase may begin with different assumptions about affordability. Exploring the same loan categories together can expose those assumptions before they become an argument or an application. I would still keep the final discussion grounded in household income, emergency savings, existing debts, and realistic future expenses rather than in the app’s convenience.
For a younger user or someone new to borrowing, the Everyone rating and straightforward finance focus make it approachable, but approachability should lead to education rather than rushed action. I would encourage a new borrower to learn the difference between rate, payment, fees, and total cost before treating any option as attractive. The app can help start that learning process; it should not be the final teacher.
My final recommendation
Rate: Home, Finance & Wellness is best understood as a focused research companion for borrowing and home-related decisions. I appreciate the way it places several relevant loan paths together and adds travel and wellness context without charging for the app itself. Its strong user response, broad install base, and clear finance identity make it worth trying when a major financial question is already on my mind.
My recommendation comes with a firm boundary: I would use it to prepare, compare categories, and organize questions, but I would not let it make the decision for me. The most important work still happens when I examine complete terms, compare outside options, and test the payment against my real budget and future plans.
For a person actively exploring a mortgage, refinance, home-equity option, auto loan, or personal loan, I think installing it is reasonable and potentially helpful. For someone wanting a full personal-finance dashboard or a dedicated travel and wellness tool, I would choose something more specialized. In my experience, the app earns its place when it turns a vague borrowing idea into a clearer next step—provided I keep my judgment, independent comparisons, and long-term costs in view.
That is why I would recommend Rate: Home, Finance & Wellness to a friend who is beginning a serious financial decision, while reminding them not to confuse a convenient starting point with a complete answer.
FAQ
What is Rate: Home, Finance & Wellness used for?
Rate: Home, Finance & Wellness is designed to bring several practical lifestyle tools together in one app. Depending on the features available in your region, it may help you explore home-related information, organize personal finance topics, and follow wellness-oriented content. It is best viewed as a convenient information and planning companion rather than a replacement for professional financial, medical, or home-maintenance advice.
Is Rate: Home, Finance & Wellness free to download and use?
The app can generally be downloaded without an upfront charge, but some tools, content, or advanced features may require payment. Before completing registration or starting a trial, check the pricing details shown in the app store and inside the application. Pay particular attention to recurring subscriptions, renewal dates, and cancellation requirements, since free trials can automatically convert into paid plans.
Can I rely on the app for financial or wellness decisions?
Rate: Home, Finance & Wellness may provide useful guidance, comparisons, reminders, or educational material, but its information should not be treated as personalized professional advice. Financial circumstances, health conditions, and home-related needs vary considerably from person to person. Verify important details independently and consult a qualified financial adviser, healthcare professional, or home specialist before making decisions with significant consequences.
What personal information does Rate: Home, Finance & Wellness collect?
The information collected can depend on the features you use, your device settings, and the app’s current privacy policy. You may be asked for account details, preferences, usage information, or data needed to personalize recommendations. Before creating an account, review the permissions and privacy documentation carefully, especially if the app requests access to location, contacts, notifications, or other sensitive device information.
Is Rate: Home, Finance & Wellness available on both Android and iPhone?
Availability may differ by operating system, country, language, and version of the service. Check the official Google Play Store or Apple App Store listing for your device to confirm compatibility, supported features, and the latest update requirements. If a feature appears on one platform but not the other, this may be caused by staged releases, regional restrictions, or differences between Android and iOS.


